- 0
- 2,447 words
/* Basic styling for readability – not part of the ‘clean HTML’ request but good practice for display */
body {
font-family: ‘Segoe UI’, Tahoma, Geneva, Verdana, sans-serif;
line-height: 1.6;
margin: 20px auto;
max-width: 900px;
color: #333;
background-color: #f9f9f9;
}
h1 {
color: #2c3e50;
text-align: center;
margin-bottom: 40px;
}
h2 {
color: #34495e;
border-bottom: 2px solid #ecf0f1;
padding-bottom: 10px;
margin-top: 30px;
}
h3 {
color: #2980b9;
margin-top: 25px;
}
p {
margin-bottom: 15px;
}
ul {
list-style-type: disc;
margin-left: 20px;
margin-bottom: 15px;
}
li {
margin-bottom: 5px;
}
Building a solid foundation for your financial future is one of the most empowering steps you can take in life. This comprehensive guide will walk you through the actionable steps needed to achieve lasting financial security, inspired by the wisdom of individuals like Former HK actor Liu Wai Hung, who prioritized long-term stability over immediate career pressures.
What You’ll Need
Embarking on this journey requires more than just money; it demands a shift in mindset and a commitment to discipline. Here’s a list of essentials to get you started:
- Commitment and Discipline: Financial security is a marathon, not a sprint. Be prepared for consistent effort.
- Patience: Compounding takes time. Don’t expect overnight results.
- Basic Financial Documents: Bank statements, credit card statements, loan agreements, investment summaries, pay stubs, and tax returns will be crucial for your initial audit.
- Access to Banking and Investment Tools: Online banking, budgeting apps, and potentially a brokerage account will be your practical instruments.
- Internet Access: For research, financial news, and managing online accounts.
- A Notebook or Digital Spreadsheet: To track progress, set goals, and manage your budget.
- An Open Mind: Be willing to learn, adapt, and challenge your existing financial habits.
Steps
Step 1: Conduct a Comprehensive Financial Audit
Before you can chart a course, you need to know exactly where you stand. This initial audit is your financial GPS, pinpointing your current location. Gather all your financial statements from the past few months: bank accounts, credit cards, loans (student, auto, mortgage, personal), and any investment accounts. List all your assets, which include cash in checking/savings, investments, retirement funds, real estate, and even valuable personal possessions. Simultaneously, detail all your liabilities – every debt you owe. Calculate your net worth by subtracting your total liabilities from your total assets. Beyond just numbers, meticulously track your income sources and categorize your expenses. Differentiate between fixed expenses (rent, loan payments) and variable expenses (groceries, entertainment). Understanding your cash flow – where your money comes from and where every dollar goes – is the foundational step to gaining control and identifying areas for improvement. You might be surprised by what you uncover, and this clarity is your most powerful tool.
Step 2: Define Your Vision for Financial Security
What does “long-term financial security” truly mean to you? For some, it’s a debt-free retirement by a certain age; for others, it’s the freedom to pursue passions without financial stress, or perhaps owning a home outright and having a substantial passive income stream. This step is about envisioning your ideal future and translating that vision into concrete, measurable goals. Sit down and reflect deeply. Write down your short-term (1-3 years), mid-term (3-10 years), and long-term (10+ years) financial aspirations. Use the SMART framework: ensure your goals are Specific, Measurable, Achievable, Relevant, and Time-bound. For example, instead of “save more money,” aim for “save $50,000 for a down payment on a house within five years.” These clearly defined goals will serve as your motivation and guide every financial decision you make moving forward.
Step 3: Master Your Cash Flow with a Practical Budget
A budget isn’t about restricting your life; it’s about giving every dollar a job and ensuring it works towards your financial goals. Based on your financial audit from Step 1, it’s time to create a realistic and actionable budget. There are various methods: the 50/30/20 rule (50% needs, 30% wants, 20% savings/debt repayment), zero-based budgeting (every dollar is allocated), or the envelope system (physical cash for categories). Choose one that resonates with you and stick to it for at least a month to see how it fits. Track every single expense, no matter how small. Identify areas where you can cut back without feeling deprived. Perhaps you can reduce dining out, find a cheaper phone plan, or cancel unused subscriptions. The goal is to ensure your income consistently exceeds your expenses, creating a surplus that can be directed towards savings, investments, and debt repayment. Review your budget regularly and adjust it as your income or expenses change.
Step 4: Build a Robust Emergency Safety Net
Life is unpredictable, and unexpected expenses can derail even the most carefully laid plans. This is where an emergency fund comes in – it’s your financial shock absorber. The goal is to save enough money to cover 3 to 6 months of essential living expenses (rent/mortgage, utilities, food, transportation, insurance) in a separate, easily accessible, high-yield savings account. If you’re self-employed, have an unstable income, or have dependents, you might aim for 9-12 months. This fund should be liquid and untouched for anything other than a true emergency, such as job loss, a major medical bill, or an unforeseen home repair. Set up an automatic transfer from your checking account to your emergency fund each payday. Seeing this fund grow provides immense peace of mind and prevents you from resorting to high-interest debt when life throws you a curveball.
Step 5: Strategically Tackle and Eliminate Debt
Debt, especially high-interest debt like credit card balances, acts like a financial anchor, dragging down your progress towards security. It’s crucial to develop a strategic plan to eliminate it. List all your debts, noting the interest rate and minimum payment for each. Two popular methods for tackling debt are the debt snowball and debt avalanche. The debt snowball involves paying off the smallest debt first to build momentum, while the debt avalanche prioritizes debts with the highest interest rates, saving you more money in the long run. Choose the method that best suits your psychology and stick to it. Explore options like consolidating high-interest debts into a lower-interest personal loan or negotiating with creditors for better rates. While working to pay down existing debt, commit to avoiding new, unnecessary debt. Freeing yourself from the burden of debt will liberate a significant portion of your income, which can then be redirected towards building wealth.
Step 6: Cultivate a Smart Investment Strategy for Growth
Once your emergency fund is solid and high-interest debt is under control, it’s time to put your money to work through investing. Inflation erodes the purchasing power of cash over time, so simply saving isn’t enough; your money needs to grow. Educate yourself on different investment vehicles such as stocks, bonds, mutual funds, and exchange-traded funds (ETFs). Understand your personal risk tolerance – how comfortable you are with the potential ups and downs of the Market. Diversification is key: don’t put all your eggs in one basket. Spread your investments across different asset classes, industries, and geographies to mitigate risk. For beginners, low-cost index funds or robo-advisors can be excellent starting points, offering diversified portfolios with minimal effort. Adopt a long-term perspective and practice dollar-cost averaging (investing a fixed amount regularly) to smooth out market fluctuations. Consistency and patience are your best allies in the investment world.
Step 7: Prioritize and Plan for Your Retirement
Retirement might seem a long way off, but it’s arguably the most critical long-term financial goal. The earlier you start, the more powerful compound interest becomes. Research the retirement accounts available in your region (e.g., 401(k), IRA, Roth IRA in the US; MPF in Hong Kong; superannuation in Australia). Maximize your contributions, especially if your employer offers a matching program – that’s essentially free money! Use online calculators to estimate how much you’ll need to save to maintain your desired lifestyle in retirement, factoring in inflation and healthcare costs. If your current savings rate isn’t on track, adjust your budget and investment strategy accordingly. Consider consulting a financial advisor to help you navigate complex retirement planning strategies, especially as you get closer to retirement age. Your future self will thank you for starting early and consistently contributing to your retirement nest egg.
Step 8: Safeguard Your Wealth and Health with Insurance
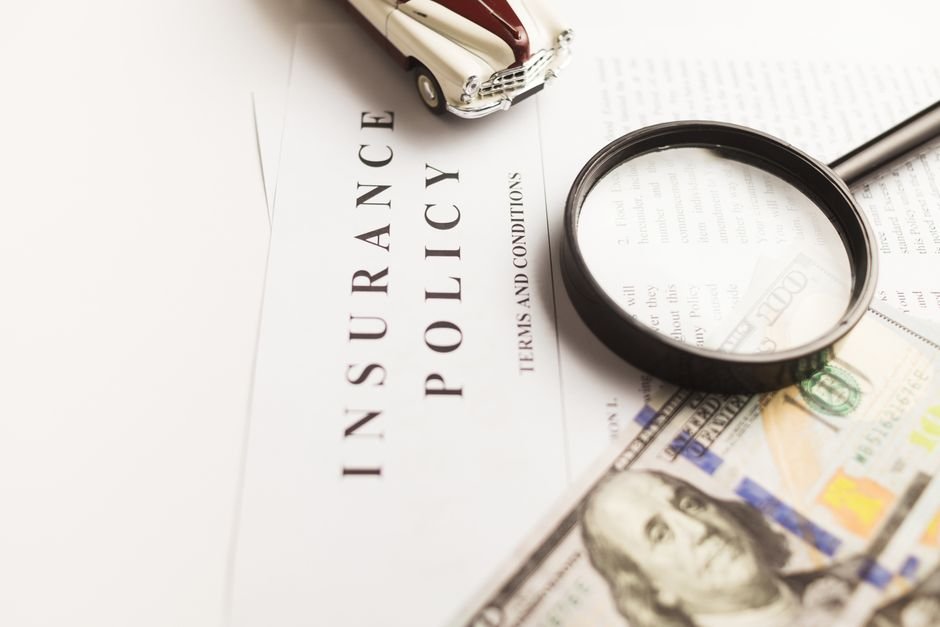
Even with a robust emergency fund and a smart investment strategy, a single catastrophic event can unravel years of financial progress. Insurance acts as a critical safety net, protecting your assets and income from unforeseen circumstances. Review your insurance needs comprehensively: health insurance is paramount to cover medical emergencies; life insurance provides financial security for your loved ones if you’re no longer around; disability insurance protects your income if you become unable to work; and home, renters, and auto insurance safeguard your property and liability. Understand the terms, deductibles, and coverage limits of each policy. Don’t just buy the cheapest option; ensure you have adequate coverage to truly protect yourself and your family. Regularly review your policies to ensure they still meet your needs as your life circumstances change (e.g., marriage, children, new home). This proactive protection is an investment in your peace of mind.
Step 9: Explore and Develop Multiple Income Streams
Relying solely on a single income source, no matter how stable it seems, can leave you vulnerable. Developing multiple income streams provides greater financial resilience and accelerates your path to security. Think about your skills, hobbies, and interests. Could you turn a passion into a side hustle, like freelance writing, graphic design, tutoring, or consulting? Perhaps you could explore passive income opportunities, such as investing in dividend-paying stocks, creating digital products, or even a rental property if you have the capital. Some people find success in e-commerce or online content creation. The goal isn’t necessarily to replace your primary income, but to diversify your revenue sources. This not only adds to your savings and investment potential but also offers a buffer against job loss or economic downturns, much like Liu Wai Hung sought alternative ventures beyond his acting career.
Step 10: Regularly Review, Adapt, and Stay Informed
Financial planning isn’t a one-time task; it’s an ongoing process. Life changes, economic conditions shift, and your goals may evolve. Schedule regular financial reviews – at least once a year, or more frequently if there are significant life events like a new job, marriage, or birth of a child. During these reviews, check your progress against your defined goals, reassess your budget, rebalance your investment portfolio, and update your insurance policies and beneficiaries. Stay informed about economic trends, tax law changes, and new financial products that could benefit you. Read reputable financial news, listen to podcasts, or even consider a periodic check-in with a trusted financial advisor. Being proactive and adaptable ensures your financial plan remains relevant, effective, and continuously aligned with your evolving vision for long-term financial security.
Tips and Common Mistakes
Helpful Tips for Your Journey:
- Start Early: The power of compound interest is immense. The sooner you start saving and investing, the less you’ll need to contribute later.
- Automate Everything: Set up automatic transfers for savings, investments, and debt payments. “Set it and forget it” removes the temptation to spend.
- Seek Professional Advice: For complex situations (e.g., estate planning, advanced investment strategies), a qualified financial advisor can provide invaluable guidance.
- Educate Yourself Continuously: Financial literacy is an ongoing process. Read books, articles, and reputable financial news sources.
- Celebrate Small Wins: Acknowledge your progress, no matter how small. It helps maintain motivation on a long journey.
Common Mistakes to Avoid:
- Procrastination: Delaying financial planning is perhaps the biggest mistake. Time is your most valuable asset.
- Emotional Investing: Making investment decisions based on fear or greed, rather than a sound strategy, often leads to losses.
- Ignoring Small Expenses: The “latte factor” is real. Small, frequent purchases can add up to significant amounts over time.
- Not Having an Emergency Fund: Without one, unexpected costs can force you into debt and derail your progress.
- Failing to Review Your Plan: Life changes, and your financial plan needs to adapt. A static plan quickly becomes an outdated plan.
- Comparing Yourself to Others: Everyone’s financial journey is unique. Focus on your own goals and progress, not someone else’s highlight reel.
Final Thoughts
Achieving long-term financial security is a journey that requires commitment, patience, and continuous learning. By systematically implementing these steps, you are not just building wealth; you are building resilience, freedom, and peace of mind. Remember, every small step you take today contributes to a more secure and fulfilling future. Embrace the process, stay disciplined, and enjoy the profound sense of empowerment that comes from taking control of your financial destiny.
Frequently Asked Questions
Where should I begin if I want to improve my long-term financial security?
The initial and most crucial step is to conduct a comprehensive financial audit. This involves gathering all your bank, credit card, loan, and investment statements from recent months to understand your current financial position. By listing all assets and detailing all liabilities, you create a clear financial GPS to guide your future planning.
Besides money, what non-financial elements are essential for achieving lasting financial security?
Achieving lasting financial security requires more than just financial resources; it demands a significant shift in mindset. Key essentials include unwavering commitment and discipline, as financial security is a marathon requiring consistent effort. Patience is also vital, as the benefits of compounding take time, alongside an open mind to learn and adapt your existing financial habits.
How does a comprehensive financial audit help me chart a course for my future?
A comprehensive financial audit acts as your financial GPS, precisely pinpointing your current economic location. By detailing all assets and liabilities, you gain a clear, objective picture of your financial health. This foundational understanding is indispensable for setting realistic goals, identifying areas for improvement, and effectively charting a strategic course towards long-term financial security.
Author

96livemarketing@gmail.com
Related Posts
Pavé the way – theedgemalaysia.com
- 0
- 2,835 words
⏱13 min readOn this pageWhat You’ll NeedTools:Materials:StepsPlan Your Project and Design Your SpacePrepare the Site: ExcavationInstall Geotextile FabricLay the Base MaterialInstall Edge...
Read out all
England thrash Croatia to put World Cup heartbreak firmly behind them – ESPN
- 0
- 2,537 words
⏱12 min readOn this pageWhat You’ll NeedSteps1. Understand the Weight of Past Disappointment2. Grasp the Pre-Match Narrative and Stakes3. Identify the Tactical...
Read out all
Many docs quit after postings – The Star
- 0
- 2,144 words
⏱9 min readOn this pageWhat You’ll NeedSteps1. Understand the Root Causes Through Data and Dialogue2. Enhance Early Career Support and Mentorship Programs3....
Read out all
ICJ? Asean? Civil suits? What can Malaysia, others do about Indonesia’s choking haze? – Malay Mail
- 0
- 2,183 words
⏱9 min readOn this pageWhat You’ll NeedSteps1. Strengthen Bilateral Diplomacy and Dialogue with Indonesia2. Fully Leverage ASEAN Mechanisms and Agreements3. Enhance Monitoring,...
Read out all
V of BTS signs as Nothing global brand ambassador – Lifestyle Asia Hong Kong
- 0
- 2,290 words
⏱10 min readOn this pageWhat you’ll needSteps1. Understand the Core Entities: V and Nothing2. Locate and Scrutinize the Official Announcement3. Analyze the...
Read out all
Avoid the F1 rush: AirAsia advises extra KLIA travel time Oct 2-4 – Malay Mail
- 0
- 2,293 words
⏱10 min readOn this pageWhat You’ll NeedSteps to a Smoother KLIA ExperienceStep 1: Grasp the Grand Prix Impact and Key DatesStep 2:...
Read out all